Paysoft is a South African business payments platform built for companies that need to pay salaries and suppliers, collect debit orders, verify bank and identity details, and keep track of transactions without doing everything manually through a bank portal.
It is really aimed at businesses rather than consumers. Think finance teams, accountants, schools, NPOs and companies processing regular payment or collection batches.
Paysoft has operated in South Africa since 2012 and currently offers EFT and real-time payments, Debit Orders, DebiCheck, Registered Mandates, bank-account verification, ID verification, Xero integration and a dedicated Paysoft Impact service for NPOs and schools.
What Is Paysoft?
Paysoft is a South African third-party payment processor. In practical terms, it gives businesses one place to handle outgoing payments, incoming collections, verification and reporting instead of splitting those jobs between payroll software, online banking, spreadsheets and manual reconciliation.
Paysoft (Pty) Ltd is a South African company with registration number 2008/236887/23. Its current business address is in Century City, Cape Town.

🏆10 Best Forex Brokers in South Africa
| Rank | Broker | Broker Review | Regulators | Minimum Deposit | Visit Broker |
|---|---|---|---|---|---|
| 🥇 |  | Read Review | ASIC, FSA, CBI, BVI, FSCA, FRSA, CySEC, ISA, JFSA | $100 | Visit Now |
| 🥈 |  | Read Review | FSCA, FCA, DFSA, FSA, CMA | $0 | Visit Now |
| 🥉 |  | Read Review | CySEC, IFSC, DFSA, FCA | $5 | Visit Now |
| 4 |  | Read Review | ASIC, CySEC, FSA, SCB | $0 | Visit Now |
| 5 |  | Read Review | BVI FSC | $0 | Visit Now |
| 6 |  | Read Review | FSA, FSC, FSCA, ASIC, CMA | $20 | Visit Now |
| 7 |  | Read Review | CBCS, FSA, FSCA, CMA | $10 | Visit Now |
| 8 |  | Read Review | ASIC, CySEC, FSCA, FSA, FSC, CMA | $100 | Visit Now |
| 9 |  | Read Review | CySEC, MWALI, FSCA | $25 | Visit Now |
| 10 |  | Read Review | FSA, CySEC, FSCA, FSC | $10 | Visit Now |
Is Paysoft Legit in South Africa?
Yes. Paysoft is an established South African payment-processing business operating inside the country's formal National Payment System.
The South African Reserve Bank oversees the National Payment System and specifically regulates categories such as Third-Party Payment Providers and System Operators.
Paysoft says it is registered as both a Third-Party Payment Provider and a System Operator, and its published information lists System Operator number SO001083.
Paysoft Overview
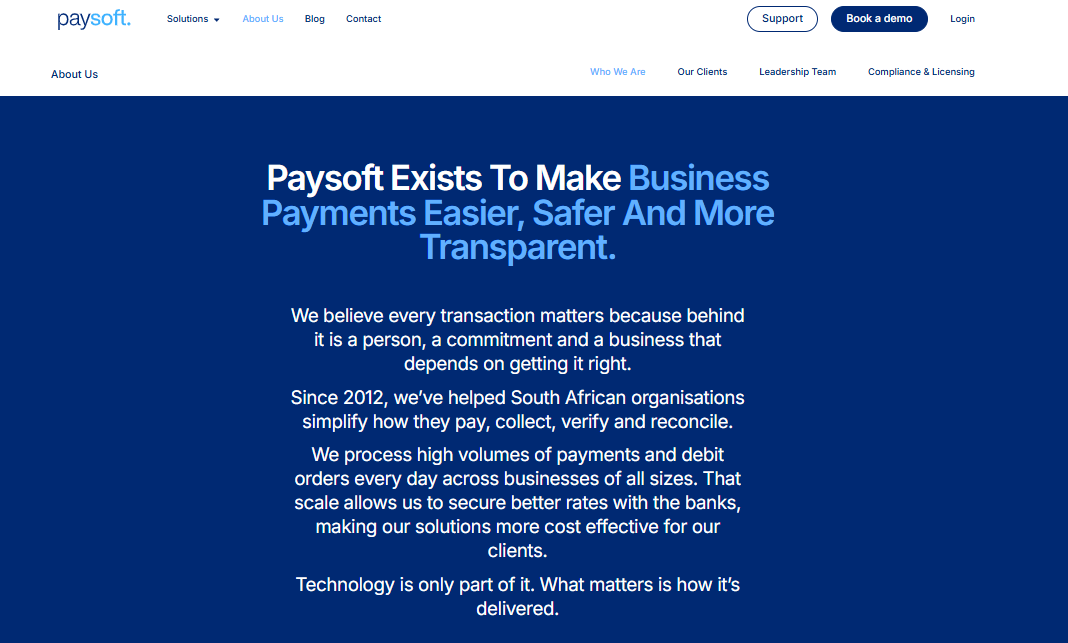
- Paysoft has been operating in South Africa since 2012, helping businesses manage payments, collections, verification and reconciliation from one system.
- Its services are built mainly for companies that need more control over regular payment runs, debit orders and finance workflows rather than for individual consumers.
- The business focuses heavily on South African payment infrastructure. Paysoft says it processes high transaction volumes across businesses of different sizes, which allows it to negotiate payment-processing rates with its banking partners.
- Its platform also supports multiple business workflows, including salary and supplier payments, debit-order collections, verification services and Xero integration.
| Feature | Paysoft South Africa |
|---|---|
| Company | Paysoft (Pty) Ltd |
| Country | South Africa |
| Operating since | 2012 |
| Main purpose | Business payment and collection processing |
| Business EFT payments | Yes |
| Salary payments | Yes |
| Supplier payments | Yes |
| SARS payments | Yes |
| Debit Orders | Yes |
| DebiCheck | Yes |
| Registered Mandates | Yes |
| Bank-account verification | Yes |
| ID verification | Yes |
| Xero integration | Yes |
| PayShap | Yes, through API |
| Bulk transactions | Yes |
| NPO and school solution | Paysoft Impact |
| Core pricing | Business-specific / quote-based |
| Local support | Yes |
| Location | Century City, Cape Town |
Compliance and Licensing
- Compliance is one of the more important parts of Paysoft’s offering.
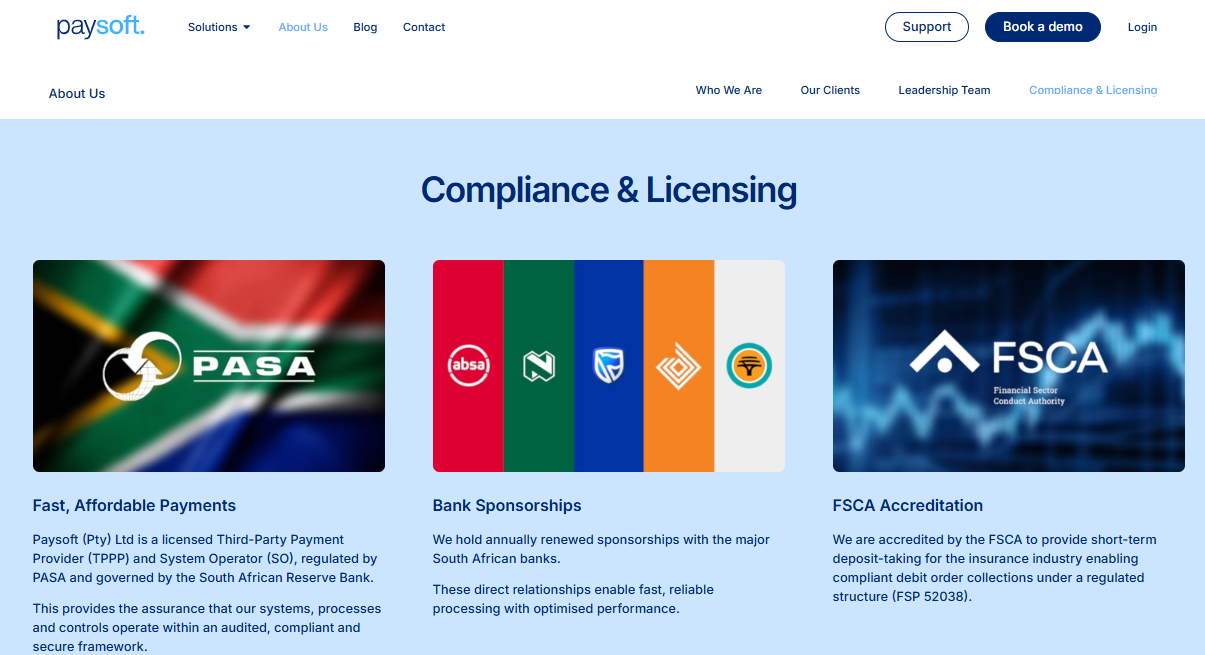
- Paysoft states that it is registered as both a Third-Party Payment Provider (TPPP) and a System Operator (SO) within South Africa’s payment environment. The company describes itself as operating under the South African payments framework, with oversight linked to the South African Reserve Bank and the Payments Association of South Africa.
- Paysoft also says it maintains renewed sponsorship relationships with major South African banks. These banking relationships support the processing infrastructure behind its payment and collection services.
- There is also an FSCA-related authorisation within the business. Paysoft states that it is accredited under FSP 52038 for short-term deposit-taking connected to the insurance industry, allowing debit-order collections to be handled within that regulated structure. This should be understood as a specific permission rather than a blanket FSCA licence covering every Paysoft service.
- For me, the main takeaway is that Paysoft is built around established South African banking and payment structures rather than operating as a standalone payment app. For a business considering the service, that matters because payment processing, debit-order collections and access controls are areas where the legal entity, banking relationships and compliance framework are just as important as the software itself.
Is Paysoft a Bank?
No, Paysoft is a payment processor, not a retail bank. It handles payment instructions and collections for businesses using its system. That distinction matters if you see the Paysoft name on a bank statement.
If you do not recognise a transaction, it does not necessarily mean Paysoft itself debited or paid you. It may mean another business used Paysoft to process the transaction.
Paysoft has a transaction-query service for exactly this reason. Consumers can use it to help identify a debit order or incoming payment processed through the Paysoft system.
What Can South African Businesses Do with Paysoft?
Paysoft is broader than a payroll-payment tool.
| Paysoft service | What it does |
|---|---|
| Payments | Pays salaries, wages, suppliers, creditors and approved beneficiaries such as SARS |
| Collections | Processes Debit Orders, DebiCheck and Registered Mandates |
| Verification | Checks bank and identity details before transactions |
| Paysoft Flow | Connects payment and reconciliation workflows with Xero |
| Paysoft Impact | Handles donations, recurring collections and Section 18A administration for NPOs and schools |
Paysoft Payments
- Paysoft Payments is designed for businesses that need to pay employees, suppliers and other beneficiaries without manually capturing every transaction in online banking.
- You can process individual payments or larger batches for salaries, wages, creditors and approved beneficiaries such as SARS.
- The platform also supports multiple approval levels, transaction reporting and audit trails.
- This is useful in a finance team where one person captures the payment batch, and someone else needs to approve it. You do not have to give one employee control over the whole payment process.
- For businesses with proper internal controls, that separation of duties is a real advantage.
Does Paysoft Support PayShap?
- Yes, Paysoft supports PayShap for immediate payments, but the current setup is API-based rather than something you simply click inside the normal Paysoft web portal. Paysoft currently describes four main payment-speed options. PayShap can handle immediate payments 24/7 through API integration.
- Real-Time Clearing works during specified processing windows and is designed to reflect in roughly 15 minutes. Same Day and Next Day payments are available when the payment is less urgent.
- That gives businesses some control over cost. There is no reason to use the fastest and usually more expensive payment rail for every transaction if a supplier only needs the money tomorrow. Paysoft Salary and Payroll Payments
- Paysoft can process salary and wage payments to employees across the major South African banks. It is important to understand what it does and does not replace.
- Paysoft is not traditional payroll software. It does not calculate PAYE, leave, overtime or gross-to-net remuneration.
- Your payroll system still works out what each employee should be paid. Paysoft handles the payment stage after those amounts have been calculated.
- The company says it supports more than 90 banking and payroll file formats, so businesses can upload data from existing payroll or accounting software rather than retyping every employee payment. For a company running a large monthly payroll, that can save a lot of admin.
- It also means Paysoft can sit alongside your current payroll system instead of forcing you to replace it.
Paysoft Salary and Payroll Payments
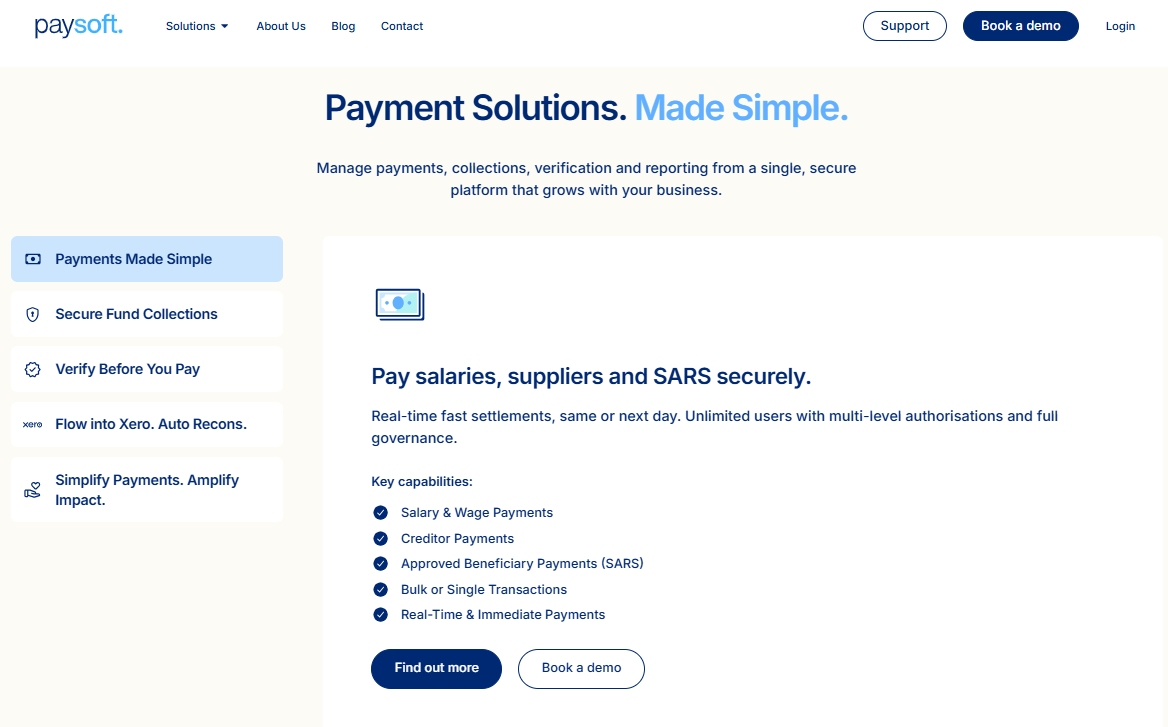
- Paysoft can process salary and wage payments to employees across the major South African banks.
- It is important to understand what it does and does not replace.
- Paysoft is not traditional payroll software. It does not calculate PAYE, leave, overtime or gross-to-net remuneration.
- Your payroll system still works out what each employee should be paid. Paysoft handles the payment stage after those amounts have been calculated.
- The company says it supports more than 90 banking and payroll file formats, so businesses can upload data from existing payroll or accounting software rather than retyping every employee payment.
- For a company running a large monthly payroll, that can save a lot of admin.
- It also means Paysoft can sit alongside your current payroll system instead of forcing you to replace it.
Paysoft Supplier and Creditor Payments
- Paysoft can also handle bulk supplier and creditor payments.
- If your finance team is paying dozens or hundreds of suppliers every month, capturing every beneficiary and payment manually through online banking gets old very quickly.
- Paysoft lets businesses process these payments in batches while keeping approval levels, transaction histories, proof of payment and reporting in the same system.
- The built-in validation tools can also catch incorrectly structured bank details before the payment is submitted.
- That matters because a rejected supplier payment creates more work for everyone. Finance has to investigate it, the supplier has to follow up and somebody eventually has to reprocess it.
Paysoft Debit Orders
- Paysoft supports recurring debit-order collections from South African bank accounts.
- Businesses can load debtor information through the web platform, file uploads, secure FTP or an API.
- Collections can then be submitted in batches, with reporting for successful, rejected and returned transactions.
- Paysoft also uses Check-Digit Validation, or CDV, to check whether the bank account and branch information follows valid South African banking rules before the debit order is submitted.
- Standard EFT debit orders can work well for memberships, subscriptions, school fees and other established recurring collections where keeping costs under control matters.
Paysoft DebiCheck
- Paysoft also supports DebiCheck.
- The big difference with DebiCheck is that the customer authenticates the debit-order mandate through their own banking channel.
- That gives the business stronger evidence that the customer agreed to the debit.
- This can be particularly useful in industries where unauthorised debit disputes are a recurring problem.
- Paysoft also supports Registered Mandates, which sit somewhere between ordinary EFT debit orders and fully authenticated DebiCheck mandates.
Debit Order vs DebiCheck vs Registered Mandate
| Collection method | Best suited to | Authentication |
|---|---|---|
| EFT Debit Order | Cost-sensitive recurring collections | Customer mandate |
| DebiCheck | Higher-trust or higher-risk collections | Customer authenticates through bank |
| Registered Mandate | Businesses wanting a bank-held digital mandate with less customer friction | Mandate registered at debtor bank |
Paysoft supports all three from the same broader collection setup.
That gives businesses some flexibility instead of forcing every customer through the same collection method.
Paysoft Bank Account Verification
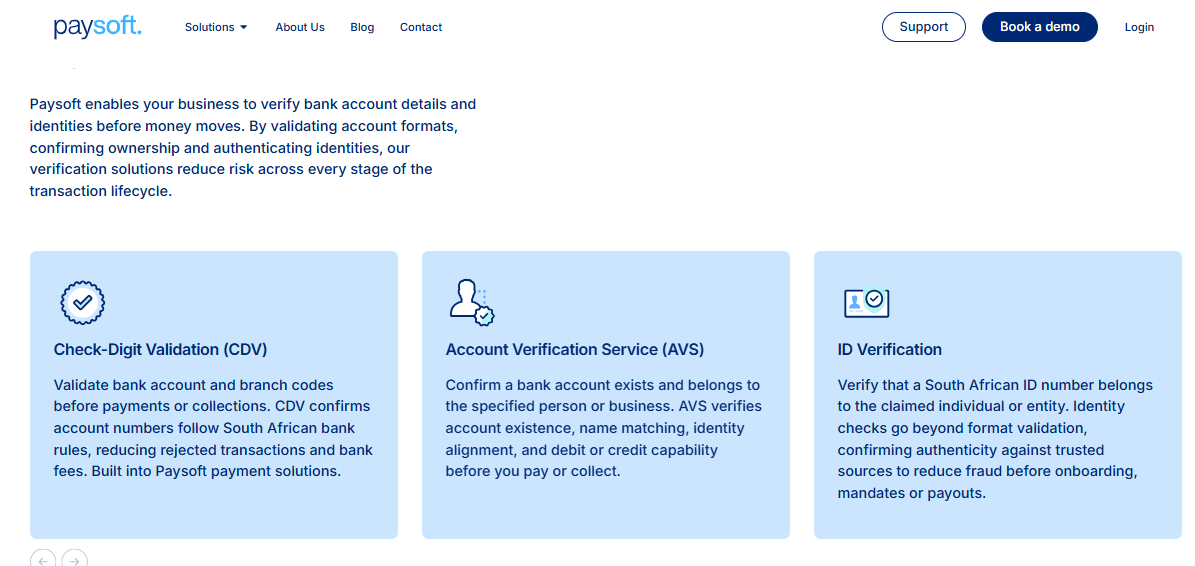
- Paysoft offers both basic account validation and more detailed bank-account verification.
- Check-Digit Validation (CDV) checks whether the bank account number and branch-code combination follows the mathematical rules used by South African banks.
- It is useful for catching obvious errors before money moves.
- Account Verification Service (AVS) goes further. It checks whether the account exists and whether the ownership details line up with the person or business information supplied.
- That can be useful before paying salaries, onboarding suppliers, processing refunds or loading debit-order instructions.
- If you are about to send a large payment to a new supplier, spending a small amount of time verifying the banking details is usually cheaper than trying to recover money sent to the wrong account.
| Paysoft Service | What It Does | Best For | Key Details |
|---|---|---|---|
| Bank Account Verification | Checks whether banking details are valid before a payment or collection is submitted. | Payroll teams, supplier onboarding, refunds and debit-order setup. | CDV checks whether the account and branch details follow valid banking rules. AVS goes further by checking whether the account exists and whether ownership details match. |
| ID Verification | Checks South African identity details against certified data sources. | Customer onboarding, supplier verification and other payment relationships. | Supports individual and batch queries. Paysoft says supplied ID details are checked against South African Department of Home Affairs data. |
| Paysoft Flow and Xero | Connects Paysoft payments and collections directly with Xero. | South African businesses already using Xero and wanting less manual reconciliation. | Reduces duplicate capturing by syncing transaction information with Xero. Available in South Africa only. Pricing includes a monthly subscription plus transaction charges. |
| Paysoft Impact | Handles payment, collection and administration workflows for NPOs, charities and schools. | Organisations managing recurring donations, school collections and Section 18A administration. | Includes recurring collections, mandate management, donor records, reporting, renewal reminders and automatic generation of qualifying Section 18A tax certificates. |
How Much Does Paysoft Cost?
- There is no single Paysoft price that applies to every business. Core payment and collection pricing depends on what you use and how many transactions you process.
- Paysoft says it can use its aggregated payment volume to negotiate better transaction rates with banking partners, but your actual cost still depends on the quote.
- Paysoft Flow is more transparent about the pricing model. It charges a monthly subscription plus variable transaction costs.
- Bank Account Verification can be used through prepaid top-ups or monthly billing.
- If you are considering Paysoft, ask for pricing based on your real monthly volumes.
- A business doing 200 transactions a month should not compare pricing in the same way as one doing 20,000.
Is Paysoft Cheaper Than Using a Bank Directly?
It can be, but I would not assume it. Paysoft says its combined processing volume allows it to negotiate better bank rates and pass some of that saving on to customers. The company also gives examples of smaller businesses saving on monthly banking costs after switching.
Those are Paysoft's own examples, though. They are not a guarantee that your company will save money.
The proper comparison should include:
- Paysoft subscription or platform fees
- Per-transaction charges
- Your current bank fees
- Staff time spent capturing payments
- Rejected-payment costs
- Reconciliation workload
- Any integration costs
A service can be slightly more expensive per transaction and still save the business money if it removes several hours of manual finance work every month.
Paysoft vs Normal Business Online Banking
| Feature | Paysoft | Typical direct banking workflow |
|---|---|---|
| Bulk salary and supplier payments | Yes | Usually |
| Multiple approval levels | Yes | Depends on bank/package |
| Debit-order processing | Yes | Depends on business banking product |
| DebiCheck | Yes | Depends on bank setup |
| Registered Mandates | Yes | Depends on provider |
| AVS/CDV verification | Built into Paysoft services | Varies |
| Xero payment/reconciliation workflow | Paysoft Flow | Depends on bank/integration |
| NPO Section 18A tools | Paysoft Impact | Generally separate |
| API processing | Yes | Depends on bank |
| Cross-bank processing | Designed around multiple SA banks | Usually tied to banking relationship |
Is Paysoft Secure?
Paysoft says financial data is encrypted and that its systems are hosted in a biometrically secured data-centre environment.
Its verification material also says systems are regularly audited by banking partners.
On the business side, the platform includes role-based access, approval levels and audit reporting.
Those controls matter when several employees can create, approve or monitor payments.
No payment platform removes operational risk completely, though.
Businesses still need sensible approval limits, strong passwords, controlled access and proper checks when bank details change.
The software can help with controls. It cannot fix a weak internal finance process on its own.
Who Should Use Paysoft?
Paysoft makes the most sense for South African organisations processing enough payments or collections for manual banking to start becoming inefficient.
Good use cases include:
- Businesses running regular salary or supplier batches
- Companies collecting subscriptions or instalments
- Finance teams that need more than one payment approver
- Xero users who want less manual reconciliation
- NPOs and schools managing recurring donations and Section 18A administration
It is probably less useful for a sole proprietor sending a handful of EFTs every month if the existing bank portal already does the job at a reasonable cost.
Pros and Cons
| ✅Pros | ❌Cons |
|---|---|
| Built around South African payment workflows | No simple public universal price list |
| Salary, supplier and SARS payments | Business-focused rather than consumer-focused |
| Debit Orders, DebiCheck and Registered Mandates | Some services require setup and onboarding |
| CDV and AVS verification | PayShap currently requires API integration |
| Multi-user approval controls | Actual savings depend on volume and current banking costs |
| Direct Xero integration | Paysoft Flow is South Africa-only |
| API, file upload and web-platform access | Advanced integrations may need technical work |
| Dedicated Paysoft Impact platform | The number of products can make initial setup more involved |
| South African support | Core pricing normally requires a quote |
| Can work alongside existing payroll and accounting software | Businesses still need proper internal payment controls |
How Do You Get Started with Paysoft?
Businesses can request a demo or contact Paysoft with their organisation details and the services they are interested in.
The onboarding form covers products such as payments, collections, verification, Xero integration and Paysoft Impact.
Before signing up, I would ask for a written fee schedule.
I would also confirm settlement times, payment types, collection methods, any debit-order security requirements and what integrations your current accounting or payroll setup will need.
That way you know the real cost and workflow before you start moving payment operations across.
Finale says about Paysoft
Paysoft makes a lot of sense for South African businesses that have outgrown basic online banking and need a more organised way to pay, collect and reconcile money.
Its strongest point is how much of the local payment workflow sits in one system.
A business can pay salaries and suppliers, collect recurring revenue through Debit Orders or DebiCheck, verify bank details before money moves and link transactions back into Xero.
That is useful if your finance team is currently doing those jobs across several unrelated platforms.
The South African focus is another plus.
Paysoft supports local banking rails, SARS payments, DebiCheck, Registered Mandates, PayShap through API, local ID verification and a dedicated NPO product built around Section 18A requirements.
The weak point is pricing transparency.
There is no simple public tariff showing exactly what every Paysoft service costs, so you cannot properly compare it with a bank or another provider without requesting a quote.
Paysoft Flow, for example, combines a monthly subscription with transaction charges.
You Might Also Like:
Best Cryptocurrencies under one cent
Best Cryptocurrency Funds and ETFs in South Africa
Frequently Asked Questions
What is Paysoft?
Paysoft is a South African business payments platform used for EFTs, salaries, supplier payments, debit-order collections, verification and transaction reporting.
Is Paysoft a South African company?
Yes. Paysoft (Pty) Ltd is incorporated in South Africa and operates from Century City in Cape Town. Its published registration number is 2008/236887/23.
Is Paysoft regulated?
Paysoft says it operates as a registered Third-Party Payment Provider and System Operator within South Africa's payments framework.
The South African Reserve Bank regulates and oversees Third-Party Payment Providers, System Operators and other participants in the National Payment System.
Is Paysoft a bank?
No. Paysoft is a payment processor. It handles payment and debit-order instructions for businesses but is not a retail bank.
Can Paysoft process salaries?
Yes. Businesses can use Paysoft to process salary and wage payments across major South African banks, including bulk payroll runs.
Can Paysoft pay SARS?
Yes. Paysoft Payments supports payments to SARS and other approved public beneficiaries.
Does Paysoft do debit orders?
Yes. Paysoft supports standard EFT Debit Orders, DebiCheck and Registered Mandates.
Does Paysoft support DebiCheck?
Yes. With DebiCheck, the customer authenticates the debit-order mandate through their own banking channel.
Does Paysoft integrate with Xero?
Yes. Paysoft Flow connects payments and collections with Xero and is currently available to South African businesses.
Does Paysoft support PayShap?
Yes, through API integration. PayShap is not currently available directly from the standard Paysoft web portal.
How much does Paysoft cost?
There is no one public price for every Paysoft service. Pricing depends on the products used and transaction volumes.
Paysoft Flow uses a monthly subscription plus transaction charges.
Does Paysoft verify bank accounts?
Yes. Paysoft offers CDV validation and Account Verification Services that can check banking details before a payment or collection is submitted.
Can Paysoft verify a South African ID?
Yes. Paysoft's ID Verify service is designed to check South African identity details using certified data sources and can handle both individual and batch queries.
Is Paysoft suitable for small businesses?
It can be. Paysoft works with businesses at different transaction volumes, including smaller clients.
Whether it is good value for a small business depends on the quote and how much manual payment administration it replaces.
Is Paysoft suitable for NPOs?
Yes. Paysoft Impact is specifically designed for South African NPOs, charities and schools.
It includes recurring donation collections, donor records, mandate management, reporting and Section 18A certificate functionality.
What should I do if Paysoft appears on my bank statement?
If you do not recognise a debit or payment showing Paysoft, use Paysoft's transaction-query service.
Paysoft may simply have processed the transaction for another company, so the query can help identify the organisation behind it.
Methodology
This page was fact-checked in 2026 using Paysoft's current company, payments, collections, verification, Xero and nonprofit product information, together with South African Reserve Bank material covering National Payment System oversight.
Where a claim about features, pricing benefits or business savings comes directly from Paysoft and could not be independently verified, it is treated as a Paysoft claim rather than presented as an independently proven result.
You Might Also Like
Recommended brokers